


Jensen Huang had the worst week of any man in a famous jacket since Tiger Woods in 2009.
Tiger’s began with a car crash outside his house and ended with his sponsors abandoning him. Jensen’s began with an affair with an alleged Chinese spy, grew to three, and ended with the world’s biggest chip maker accepting his resignation.
Jensen dreamed up Nvidia in a booth at a Denny’s restaurant in 1993 and built it into a US$4 trillion company with about 60 people reporting directly to him.
A couple of them, it turns out, more directly than others.
Even Denny’s turned on him. On Thursday it took down the plaque marking the booth (they relented and put it back up the next day).
Tiger pulled on another green jacket 10 years after his week from hell, so we wouldn’t write off Jensen and the leather one either.
Golf was a smaller game while Tiger was gone, and the crowds and the TV audience went with him. It’s why we’re worried about Nvidia, which has never had another boss, and we have no idea what it looks like without him.
It makes up about 7% of the S&P 500, so if you’ve got super you’re about to find out with us.
The people running the companies in our portfolio kept their minds on the drilling this week. We sat down with Black Horse Mining’s managing director about the rig under Mt Egerton, and Exultant’s chairman put more of his own money into his company.
What caught our eye this week:
Black Horse’s rig is turning again under Mt Egerton, with assays weeks away
Bubalus director Nick Jolly has a win at his other company
Copper gets sold with the chip stocks while Shanghai’s warehouses empty
Anthropic lines up a US$1.2 trillion float, the second-biggest ever
Gold sits 30% under its record while central banks buy the most in two years
Paladin raises 35 times what Powerhaus is worth in a week
10X’s chairman buys again at half his May price
A $20 million gold company says its first pit is ready to dig
Let’s get to it.
Black Horse Walks Us Through Mt Egerton
The managing director of gold explorer Black Horse Mining (ASX: BHL) sat down in our studio this week and said investors have probably been wondering what the hell is going on.
It was rain, David Frances told us. Mt Egerton had its wettest winter on record and the ground was too wet to get a rig onto.
“We were as frustrated as anybody,” he said.
The rain has cleared and the rig is turning again, with the first hole of a 4,000 metre program nearly done and assays due at the end of November or early December.
While it rained the crew reopened a tunnel shut for 100 years and found gold the miners had left behind, in a fault 1.3 metres wide running 10.79 grams a tonne. The miners passed it over because it sat right on the cut-off of what they were mining.
Frances wanted to drill the fault first and had to start on higher ground because of the wet, so it comes next.
They also spent the weather break sheeting the roads in, so the next wet winter won’t stop the drilling.
Mt Egerton is one of only eight goldfields in Victoria to produce more than a million ounces from hard rock, and those miners got 1.29 million out before water flooded the workings in 1906.
More than 90% of the drilling since the mine shut stopped above 150 metres, and BHL’s rig can reach 1,000. Fosterville sits in the same corridor of Victorian goldfields, and its richest zone only turned up after drilling pushed past 800 metres.
Frances believes the miners left a lot more behind than one fault. Gold running three to nine grams a tonne was too low for them to bother with, and underground mines everywhere dig it today.
“That stuff’s still there,” he said. “That’s the prize for us.”
We named BHL our 2025 Small-Cap of the Year for the ground under the old mine. We think one good hole down there could move the company a long way, and BHL has up to 10 coming.
Our full chat with Frances is below.
Bubalus Director Nick Jolly Has a Win at Anax
Nick Jolly joined the board of Bubalus Resources (ASX: BUS) last month, and this week another company he sits on jumped 48%.
Jolly ran the geology at Spartan Resources while it found 2.37 million ounces of gold and sold to Ramelius for $2.4 billion last year.
He came onto the Bubalus board when it agreed to buy Skyline, a copper-gold project 10km from Mt Lyell in Tasmania, and he put his own money into the raise.
He’s also a director and exploration adviser at Pilbara copper-zinc developer Anax Metals (ASX: ANX), which he joined in June.
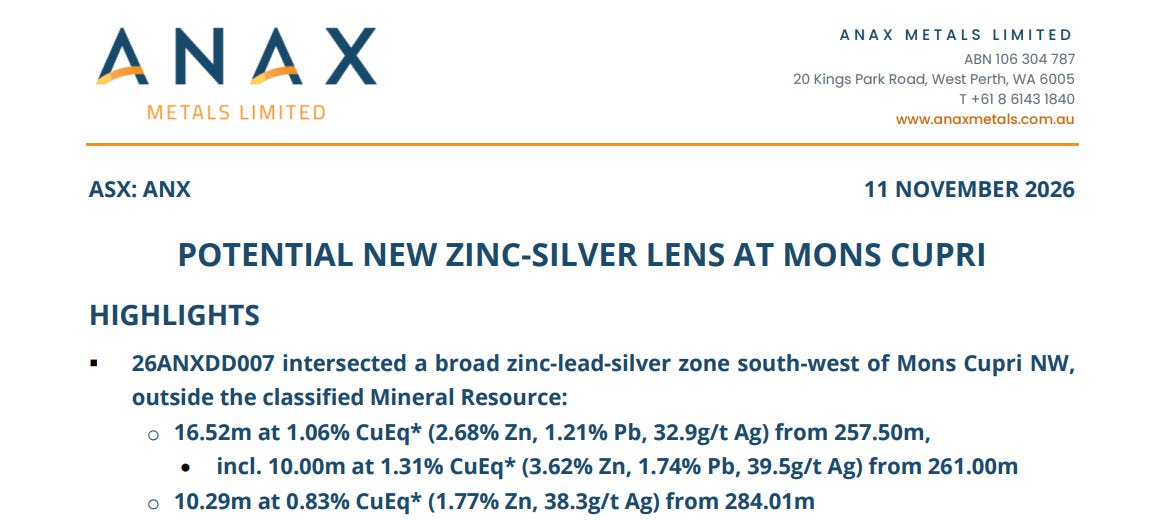
This week Anax hit what it thinks is a new zone of zinc, lead and silver outside the resource at its Mons Cupri deposit, part of the Whim Creek project about 120km from Port Hedland.
The best hole ran 16.52 metres at 2.68% zinc, 1.21% lead and 32.9 grams of silver a tonne from 257.5 metres down.
Anax shares ran from 2.7c last Friday to as high as 4c on Wednesday, and four more holes are drilling now to see whether the hits join up.
Jolly said he’s long believed Mons Cupri had more to give at depth, and now Anax gets to chase it.
Our money is in Bubalus, where the rig starts at Skyline in January, and Jolly having a win at Anax two months before it is a big tick.
Copper Falls With the Chip Stocks
Copper got dragged into Jensen Huang’s week.
Traders who were dumping Nvidia and the other AI stocks dumped copper with them, and US copper futures fell to US$6.18 a pound on Tuesday. It’s the lowest since July and about 10% under September’s record.
While the traders sold, Chinese buyers kept pulling copper out of the Shanghai exchange’s warehouses. Stocks there fell more than 24% last week to 33,848 tonnes, the lowest in almost three years.
Chile digs more copper than any other country, and with its September quarter output at a 20-year low there’s less coming out of the ground to refill them.
Freeport signed off on US$4.5 billion last week to expand its Bagdad mine in Arizona, and the copper from it won’t arrive to help until mid-2030.
We said a fortnight ago we watch the forecasts less closely than the warehouses, which are emptying. We think this week was a tech scare and the world is still short of copper.
Bubalus Resources (ASX: BUS) and Exultant Mining (ASX: 10X) both have copper drilling ahead of them, and we’re happy holding both through a dip we put down to tech stocks and general market sentiment.
Anthropic Lines Up the Second-Biggest Float Ever
We said the other week the $44 billion Firmus float that wasn’t was outside our wheelhouse, and this one is in another stratosphere.
Anthropic, the company behind the Claude AI models, wants to list on the Nasdaq this coming week at a value of about US$1.2 trillion. It’s selling 825 million shares at US$70 to US$78 each to raise about US$61 billion, and only SpaceX has ever raised more.
It made US$35.3 billion in revenue in the year to September and counts America’s 10 biggest companies as customers.

Nvidia and a group of other tech giants have agreed to buy another US$26 billion of shares at the float price. Nvidia signed two days before Jensen Huang quit.
Australia’s Macquarie is one of the 22 banks selling it.
We’re watching because what fund managers pay for AI in New York sets the mood for AI small-caps on the ASX.
The shares price on Wednesday and trade on Thursday, in the same week Nvidia reports its results without Huang. If fund managers pay the top of the range after the week AI stocks have had, we’ll take it as a sign they still want it.
Gold Takes a Hit From the Fed
Anyone who bought gold at January’s record of US$5,594 an ounce is down about 30%. It finished this week just under US$3,900, its lowest in 13 months.
The first big fall came in March, when the Iran war sent investors running to the US dollar and gold had its worst month since 2008.
This week’s fall came from the Fed, after US inflation came in hotter than expected on Tuesday and governor Christopher Waller floated a half-point rate rise for December. Gold dropped nearly 3% on the day and another 2.5% on Thursday, and traders now put the odds of a December rise at about 91%.
Investors sell gold when rates rise because they can earn close to 5% a year in US government bonds.
Central banks bought 321 tonnes of gold in the September quarter, up 42% on a year earlier and the most since the end of 2024. China and Poland led the buying.
They buy gold when they’re worried about what governments owe, and the world now owes a record US$365 trillion on the Institute of International Finance’s count. America’s own debt passed US$40 trillion in August and Washington spent a record US$1.36 trillion on interest last financial year.
The Fed lifting rates makes Washington’s bill bigger again, and we think it’s why the central banks are buying gold while everyone else sells.
We’re still bullish on gold over the long run, and we’d rather be on the same side as the central banks than the traders. Goldmans are predicting a strong rebound in the price in 2027, and so are we.
Elk Range Mining (ASX: ELK) in Idaho and Black Horse Mining (ASX: BHL) in Victoria are our two gold explorers, and both have rigs turning.
Paladin Raises $525 Million for Uranium
Fund managers handed a uranium miner $525 million this week, which is about 35 times what the uranium explorer in our portfolio is worth.
The miner is Paladin Energy (ASX: PDN), and it raised the money at $7.80 a share to keep building its next mine. Existing holders can put in up to $50 million more at the same price.

Most of it goes to Patterson Lake South, a uranium project in Saskatchewan’s Athabasca Basin, home of the richest uranium mines on earth. It won’t produce a pound until 2031, and fund managers put up half a billion dollars for it anyway.
They did it with uranium above US$91 a pound, its highest price since February. Power companies buy most of their uranium on long-term contracts, and the contract price hit US$99 at the end of October, the highest since records began in 1996.
We think some of the money finds its way down to the explorers, and ours is Powerhaus Uranium (ASX: POW).
POW’s crews are sampling a 17 square kilometre terrace of shallow uranium at Malbec in Argentina, with results due before the end of the year. Its first 5,000 metre drill program starts once the environmental permits arrive, and we expect to hear from Argentina soon.
Exultant’s Chairman Buys Again
The chairman of the smallest company in our portfolio went back into the market this week and bought more of it at about half the price he paid in May.
Brett Grosvenor is executive chairman of NSW copper-gold explorer Exultant Mining (ASX: 10X). He bought 200,000 shares on market between Monday and Thursday at just under 10c and now holds 1.45 million.
It’s his fifth buy this year. He picked up 500,000 shares across four trades in April and May, the last of them at 18.7c.
The old market line is that directors sell for all sorts of reasons and buy for only one.
Shareholders are behind him too, passing all seven resolutions at Friday’s AGM with 100% of the vote.
The next job is ground geophysics at Watsons, the copper prospect three hours west of Sydney where 10X wants to pick its first drill hole.
10X is worth under $4 million with about $2.8 million in the bank, so the market is putting not much more than $1 million on its ground. Like the chairman, we think it’s cheap.
Cavalier Says Crawford is Ready to Dig
A gold company worth about $20 million told the market on Friday its first pit is ready to dig, and its own study values the first stage at $77.2 million after tax.
Cavalier Resources (ASX: CVR) owns the Crawford gold project, 20km from Leonora in WA, which holds 117,800 ounces of gold at 1 gram a tonne.
The first stage is a shallow pit in oxide ore soft enough to dig without blasting. The ore gets crushed and stacked in a heap on site, and a solution runs through the pile and pulls the gold out.
The approvals came through in October and Cavalier signed binding term sheets for about $23 million of finance in July. This month it dug its last test pits and drilled its first water bores, and it has picked SSH Mining as its contractor with the contract close to signed.
CVR closed at 24c on Friday. We’re watching from the sidelines, and with the approvals through and the finance term sheets signed, the next news should be the diggers going in.
The Week Ahead
Nvidia hands down its quarterly results on Tuesday with finance boss Colette Kress in charge as interim chief executive (no word on whether the leather jacket comes with the job).
Anthropic prices its float the night after.
Closer to home, the October jobs figures land on Thursday. Unemployment hit 4.7% in September, and if it has kept climbing the Reserve Bank has less reason to lift rates again, which is good news for small-caps.
We’re waiting on gold assays from Elk Range and Black Horse and on Powerhaus’ results from Argentina, and the first of them could land any week now.
Till next week.